Market is saturating: Central Bank forecasts decline in loan rates over the next 3-4 years
In some cases, mortgage rates have already dropped to 18% per annum
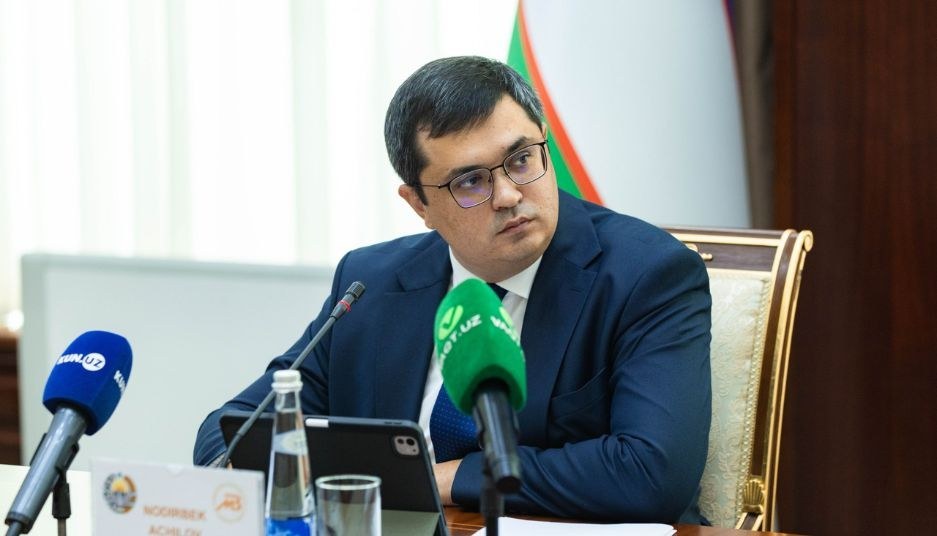
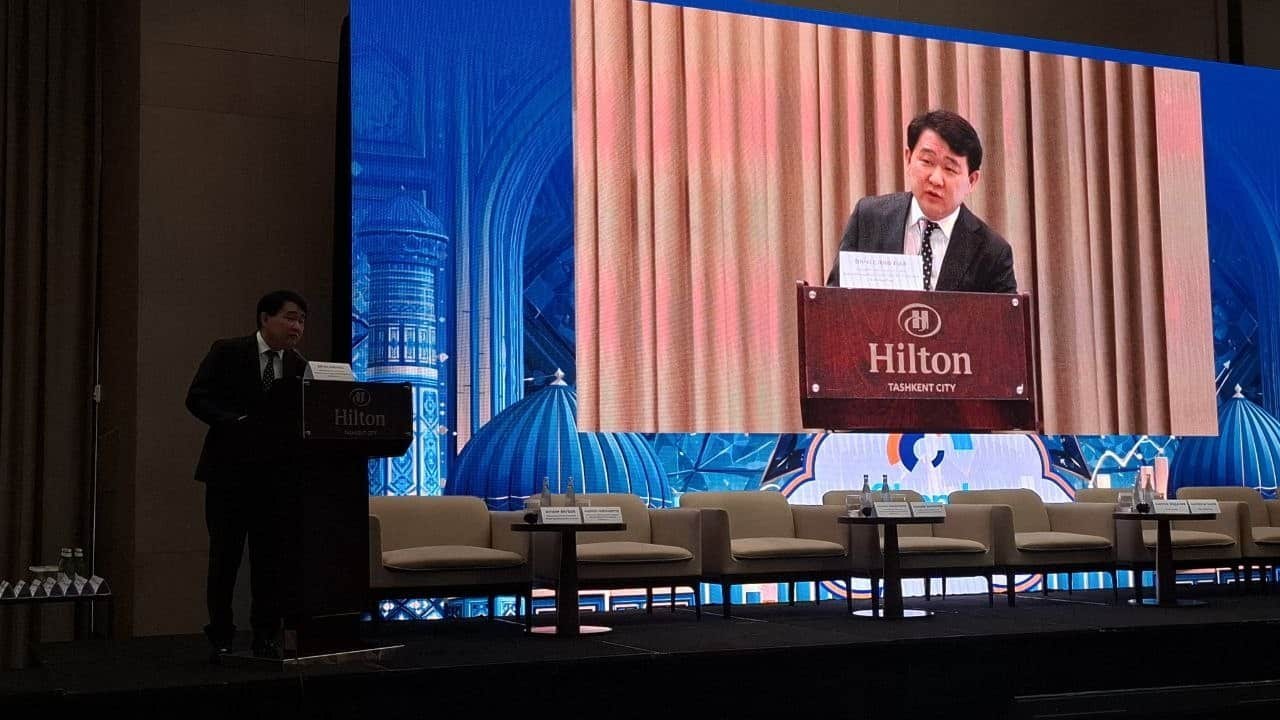
Deputy Chairman of the Central Bank Nodirbek Achilov linked the forecast to market saturation and the balancing of demand for borrowing. According to him, in recent years, rates in different segments have changed unevenly: investment loans have already become cheaper, while consumer loans, short-term and unsecured loans, as well as microloans and loans through online services, remain relatively expensive.
In mortgage lending, rates are also decreasing. If previously housing loans were offered at 24-25% per annum, now in some cases they can be obtained at 18%. At the same time, the Central Bank notes that expensive types of loans are also gradually moving toward a decline, although they may remain above the average level.
Achilov identified the resource base of banks as one of the factors affecting the cost of loans. Institutions use deposits, internal sources, and external financing for lending. Currently, the growth of bank deposits reaches 45% per year, which expands the volume of funds available for issuing loans and may increase their accessibility.
To further reduce rates, the regulator is collaborating with the International Monetary Fund and the European Bank for Reconstruction and Development. Among the areas of this work are the introduction of floating-rate instruments and the development of the money market, which should influence the cost of long-term resources.
Further reduction of the key rate, according to Achilov, will depend on inflation and inflation expectations. The Central Bank expects that increased competition among banks, the growth in the number of financial offerings, and the expansion of the resource base will help reduce the cost of loans and deposits during the forecast period.